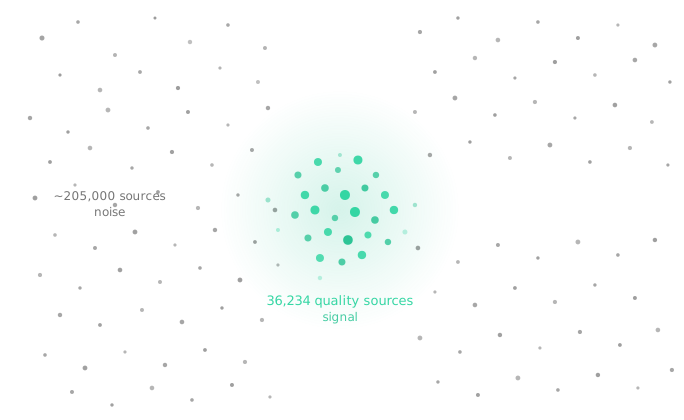
Of 241,000+ sources, only 15% carry statistically significant predictive power for equity returns. Filtering to the quality panel increases mean IC from 0.006 to 0.041 with no loss in coverage.
• +0.035 IC boostQuality sources vs unfiltered baseline
•Adaptive signal decay Each source peaks across distinct forecast horizons
• Regime-aware selection Source relevance shifts across market environments
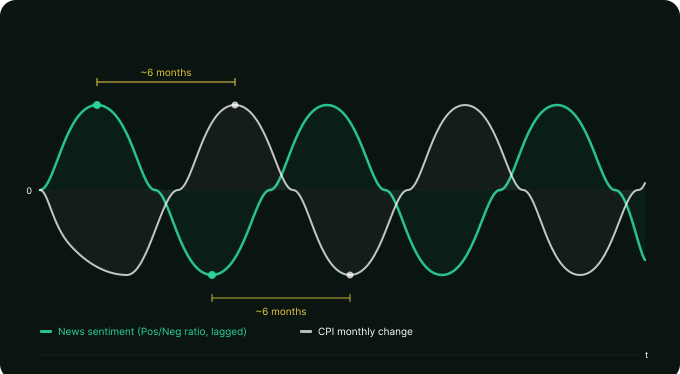
Our latest study shows that news-based sentiment provides statistically significant predictive power for U.S. CPI-U.
Adding sentiment to standard autoregressive baselines improves explanatory power and reduces forecast errors, consistent with an expectations-to-prices mechanism.
• +0.15 R² boost Improves accuracy vs baseline
•Expectations channel News tone captures pricing and demand expectations
•Regime-dependent effects Predictive strength varies across inflation cycles